Special Investigation | October 9, 2026
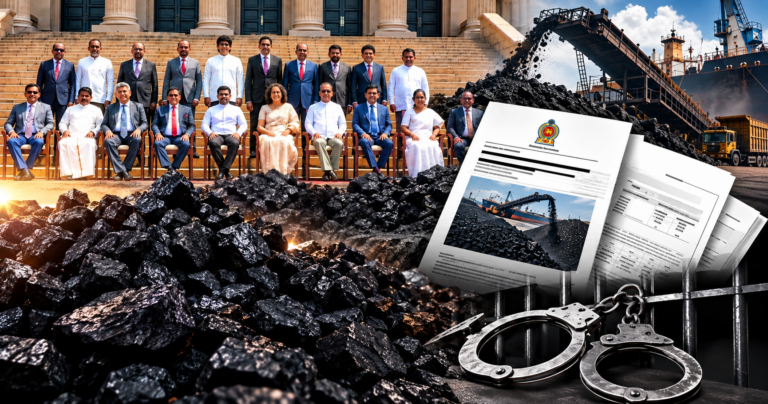
Trident Chemphar Coal Supplies Under Scrutiny as Parliamentary Committee Exposes Higher Fuel Consumption, Power Plant Damage and Costly Emergency Electricity Purchases
A parliamentary investigation has exposed serious financial and operational consequences arising from the use of substandard coal at Sri Lanka’s Lakvijaya Power Plant. The findings raise urgent questions about procurement oversight, supplier accountability, government supervision and the financial burden imposed on the country’s electricity sector.
A committee appointed by the Sectoral Oversight Committee on Infrastructure and Strategic Development of the Parliament of Sri Lanka has calculated that the use of substandard coal supplied by Trident Chemphar Ltd resulted in additional costs amounting to Rs. 15,681,292,713 — approximately Rs. 15.68 billion.
The findings, contained in a report dated October 7, 2026, represent one of the most significant documented assessments of the financial consequences associated with questionable coal supplies to the Lakvijaya Power Plant in Norochcholai.
The investigation identifies three principal sources of additional expenditure: increased coal consumption caused by quality deficiencies, additional maintenance and disposal costs, and the procurement of replacement electricity following reduced generation at the coal-fired power station.
Although the report quantifies substantial financial losses, it does not establish that criminal fraud, bribery or corruption occurred. Nevertheless, its findings raise serious questions about the effectiveness of procurement controls, contract enforcement, quality assurance and institutional accountability.
Rs. 15.68 Billion: The Financial Breakdown
The committee’s calculations identify the following additional costs arising from the coal-quality controversy.
| Category | Additional cost |
|---|---|
| Higher coal consumption due to quality variations | Rs. 7,099.43 million |
| Additional maintenance costs | Rs. 80.40 million |
| Additional ash handling and disposal | Rs. 13.10 million |
| Replacement electricity procurement | Rs. 8,572.51 million |
| Total | Rs. 15,681.29 million |
The report’s summary separates the first three categories, which together amount to approximately Rs. 7.19 billion, from the replacement-electricity costs of approximately Rs. 8.57 billion.
The combined financial impact is particularly concerning because the additional expenditure relates not to investment in new generating capacity or infrastructure improvements, but to the consequences of operational and fuel-quality problems.
The committee’s assessment covers the period from January 1 to September 15, 2026.
Trident Chemphar Ltd: The Supplier at the Centre of the Controversy
The parliamentary investigation identifies Trident Chemphar Ltd as the supplier whose coal deliveries were associated with the quality-related problems examined by the committee.The report states that the disputed supplies were received under an emergency procurement arrangement involving Lanka Coal Company (Pvt) Ltd.
According to the committee, coal supplied through this arrangement began arriving at the Puttalam anchorage in early 2026.The report records that the first shipment under the relevant procurement arrangement arrived on January 31, 2026, and began unloading on February 1.
It also states that shipments scheduled under the contract experienced difficulties because of coal-quality issues.
Of the 25 shipments associated with the arrangement, the report records that only 19 had been received by July 3, 2026, citing quality-related problems affecting the supply process.
This raises an important procurement question: Were the quality deficiencies identified early enough to allow the authorities to prevent further financial exposure?
The committee’s findings demonstrate the consequences of the coal used at the power station. However, determining whether particular officials failed to enforce contractual safeguards would require further examination of tender documents, laboratory certificates, shipment inspection reports, correspondence and contractual remedies.
Coal Quality Deficiencies Increased Fuel Consumption
One of the most significant findings concerns the quantity of coal required to produce electricity.
The committee used a standard average coal consumption rate of 0.3742 kilograms per kilowatt-hour as the benchmark for its assessment.It examined the difference between expected consumption under standard conditions and the actual consumption associated with coal supplied by Trident Chemphar Ltd.The resulting calculation attributed approximately Rs. 7.099 billion in additional coal expenditure to quality variations.
In practical terms, lower-quality coal can require a power station to burn more fuel to generate an equivalent quantity of electricity.This affects operating costs, fuel reserves, handling requirements and the efficiency of electricity generation.The report’s calculation therefore points to a substantial economic consequence extending beyond the original purchase price of the coal.
The critical issue is not simply whether the coal was cheaper or more expensive at the point of purchase. It is whether its performance made the total cost of electricity generation significantly higher.
Damage and Maintenance Problems at Lakvijaya
The investigation also identifies additional maintenance expenditure associated with the use of the coal in question.
According to the report, the power station experienced problems involving ash accumulation, boiler components and coal-handling equipment.The committee assessed additional maintenance costs at Rs. 80.4 million.The accompanying technical material describes problems involving air preheaters, ash deposits and coal mills.
The estimated expenditure includes:
- Rs. 67.5 million for dismantling, removing, cleaning and reinstalling boiler air-preheating elements.
- Rs. 11.6 million for removing accumulated ash deposits.
- Rs. 1.3 million for repairs associated with coal mills.
These figures relate to Unit 1 of the Lakvijaya Power Plant.
The report explicitly notes that equivalent assessments could not be made for the other two generating units because their internal inspections had not been completed.Consequently, the maintenance figure should not be interpreted as a comprehensive assessment of every potential maintenance consequence across the entire power station.
This limitation is important because the full extent of equipment deterioration may not be captured by the costs identified in the report.
Additional Ash Handling and Environmental Costs
The committee also calculated Rs. 13.1 million in additional ash-handling and disposal costs.
These included expenditure on additional bowser operations, ash-dumping tippers and the transportation of additional pyrites.Although relatively small compared with the billions attributed to increased coal consumption and replacement electricity procurement, these costs demonstrate how coal-quality deficiencies can affect several parts of a power station’s operating system simultaneously.
Poor fuel quality can create additional operational demands beyond the combustion process itself, including increased handling, cleaning, transportation and disposal requirements.The report’s calculations identify the associated expenditure but do not constitute a comprehensive environmental impact assessment.
Electricity Generation Shortfalls: The Largest Financial Burden
The largest individual component of the committee’s loss calculation concerns electricity procured to compensate for reduced generation at Lakvijaya.
The committee assessed the additional procurement cost at approximately Rs. 8.57 billion.
According to the report, the National System Operator (Pvt) Ltd supplied calculations concerning reductions in power-generation capacity and the financial consequences of procuring replacement electricity.These calculations covered the period from January 1 to September 15, 2026.
The investigation considered the impact of reduced coal-fired generation and the contribution of alternative generation sources, including hydropower.The financial consequences were particularly significant because the electricity system had to continue meeting demand even when Lakvijaya could not generate at its expected capacity.
In such circumstances, replacement electricity can involve more expensive generation sources.The committee’s assessment indicates that these replacement costs represented more than half of the total financial impact identified in the report.
However, an important qualification appears in the document.
Regulatory Concerns Over the Calculation
The Public Utilities Commission of Sri Lanka (PUCSL) recorded reservations concerning aspects of the replacement-generation calculations.
In particular, the regulator questioned the treatment of additional hydropower generation as having zero replacement cost.
Its position was that hydropower used to compensate for reduced coal-fired generation could have an economic value because stored water might otherwise have been available to avoid more expensive generation later.
The regulator also raised concerns about the treatment of diesel-based electricity generation, including the effect of subsidised fuel prices on the calculation of replacement costs.
These reservations do not eliminate the financial problems identified by the committee. They do, however, mean that the reported Rs. 8.57 billion replacement-generation figure should be understood as the committee’s estimate, subject to the methodological qualifications recorded in the report.
Emergency Procurement: Another Rs. 2.28 Billion in Additional Costs
A separate section of the parliamentary report examines the financial consequences of emergency coal procurement.
The committee records that five shipments were received through an emergency procurement arrangement involving M/s Taranjo Resources (Pvt) Ltd.
According to Annexure 5.1, the committee calculated an additional procurement cost of approximately US$7.21 million, equivalent to Rs. 2.284 billion, when compared with the applicable tender-price calculation.
The committee nevertheless concluded that this additional cost should not be treated as a financial loss in the same manner as the other costs identified in its principal summary.
It reasoned that the emergency procurement was undertaken to address the risk of coal shortages and interruptions to electricity generation.
The committee also noted that the failure of Trident Chemphar Ltd to supply the required coal could have contributed to the need for replacement procurement.
This creates an important distinction between additional expenditure incurred to maintain electricity supplies and financial losses directly attributed to the use of substandard coal.
The Rs. 2.284 billion emergency-procurement figure is therefore not included in the committee’s Rs. 15.68 billion loss total.
Nevertheless, the separate expenditure highlights the wider financial risks associated with failures or disruptions in coal supply.
Questions Over the Tender and Procurement Process
The findings place the coal procurement and contract-management process under intense scrutiny.
Coal procurement is not simply a commercial transaction involving the lowest available price.
The technical specifications of coal, including its calorific value, ash content and other characteristics, directly influence generating efficiency and maintenance requirements.
A tender that appears financially attractive at the purchasing stage may ultimately impose much higher costs if the supplied fuel fails to perform according to contractual standards.
The parliamentary findings therefore raise several questions requiring further investigation.
First, what quality certificates and laboratory assessments were submitted before the coal shipments were accepted?
Second, when did the responsible institutions first become aware of significant deficiencies in coal quality?
Third, what contractual penalties, compensation provisions or performance guarantees were available against the supplier?
Fourth, were those remedies invoked promptly and effectively?
Fifth, what information was communicated to the Ministry of Energy and other government authorities when the operational and financial problems emerged?
The committee’s report does not provide sufficient evidence to answer all these questions conclusively.
Their resolution would require a separate examination of the complete procurement record and the decisions taken by the officials responsible for implementing the relevant contracts.
Government Accountability: Who Was Responsible for Protecting Public Funds?
The investigation raises a broader question about institutional responsibility within Sri Lanka’s electricity sector.
Coal procurement, delivery, quality assurance, electricity generation and system operation involve several organisations operating under different responsibilities.
These include Lanka Coal Company, Electricity Generation Lanka, the Lakvijaya Power Plant management, the National System Operator and the Ministry of Energy.
The committee itself included representatives associated with these institutions.
The existence of several layers of administrative and technical responsibility makes it essential to determine where any failures occurred.
A financial loss of this magnitude cannot be adequately addressed by identifying technical deficiencies alone.
The authorities must also examine whether appropriate decisions were taken when problems were first detected and whether public institutions acted in accordance with their legal and contractual obligations.
The government bears political and administrative responsibility for ensuring that state institutions respond effectively to such findings.
That responsibility, however, should be distinguished from personal criminal liability, which cannot be established without evidence of individual misconduct and the applicable legal process.
A Concern Over the Investigation’s Independence
The report’s annexures reveal an additional issue involving the composition of the investigating committee.
In correspondence dated August 25, 2026, the Chairman of Electricity Generation Lanka raised concerns about potential conflicts of interest.
The letter questioned whether the company’s chairman should participate in the parliamentary-appointed committee when a separate internal investigation was already examining related matters.
It suggested that an appropriately qualified independent representative would be preferable.
The correspondence argued that the participation of individuals connected with institutions under examination could create perceived or actual conflicts of interest.
This is a significant governance issue.
Investigations into major financial losses must not only be technically credible but must also demonstrate sufficient independence from the organisations whose actions are being examined.
The existence of the letter does not establish that the committee’s findings were compromised. It does, however, show that concerns about the investigative structure were raised during the process.
Why the Report Matters to Electricity Consumers
The financial consequences identified by the committee are not merely accounting figures.
The costs arise within a publicly significant electricity system that ultimately depends on revenues, public financing and decisions affecting consumers and taxpayers.
Higher coal consumption increases the cost of generation.
Maintenance problems create additional expenditure and may affect the reliability of generating equipment.
Reduced output from a major coal-fired power station can require electricity to be obtained from more expensive sources.
Taken together, these effects can place pressure on the finances of the electricity sector.
However, the report does not establish that the entire Rs. 15.68 billion was directly passed on to electricity consumers through tariffs.
Any such conclusion would require a separate examination of tariff calculations, financial transfers and the treatment of these costs by the relevant authorities.
Nevertheless, the scale of the additional expenditure makes the issue one of considerable public interest.
What Should Happen Next?
The parliamentary report provides a financial assessment of the consequences associated with the disputed coal supplies.
It is not, by itself, a completed criminal investigation or a judicial determination of wrongdoing.
A comprehensive accountability process would need to establish whether contractual breaches occurred, whether recoverable losses can be claimed from the supplier, and whether any public officials failed to perform their duties.
Particular attention should be paid to the technical inspection records, the original tender specifications, the supplier’s contractual obligations and the actions taken after coal-quality problems were identified.
The authorities should also clarify whether the additional costs calculated by the committee are final or whether further technical and financial assessments remain necessary.
The separate emergency-procurement expenditure and the PUCSL’s reservations about replacement-generation calculations should be examined transparently.
Conclusion: A Rs. 15.68 Billion Warning About Procurement Governance
The October 7 parliamentary report exposes the potentially enormous financial consequences of failures in coal quality and electricity-sector procurement.
Its central finding is that the use of substandard coal supplied by Trident Chemphar Ltd was associated with additional costs estimated at Rs. 15.68 billion during the period examined.
The losses identified extend across fuel consumption, maintenance, ash handling and replacement electricity procurement.
The findings also reveal weaknesses and unresolved questions concerning procurement safeguards, technical supervision, contractual enforcement and institutional accountability.
While the report does not prove corruption or criminal misconduct, it provides substantial grounds for further investigation.
The central question is no longer merely how much Sri Lanka lost because of substandard coal. It is whether the institutions responsible for protecting public funds acted quickly and effectively enough to prevent those losses — and whether the country can recover any of the money.
Until those questions are answered through transparent and independent scrutiny, the coal controversy will remain a serious test of the government’s commitment to financial accountability and responsible management of public resources.
About the Author